Professor Heiwai Tang, Mr Cyrus Cheung, and 黃鈺琪
19 August 2026
With the artificial intelligence (AI) wave still in full swing, demand for compute hardware is soaring rapidly. Amid this technological revolution, Hong Kong’s import and export sector has successfully seized the opportunities of the era and shown strong growth momentum.
Goods trade returns to an upward trajectory
According to data from the Census and Statistics Department, Hong Kong’s import and export sector reached its previous peak in 2021, with the total value of merchandise trade surging by 25.3% year on year to surpass HK$10 trillion. The value of domestic exports reached HK$74.5 billion, representing a sharp year-on-year increase of 57.1%. However, in the following two years, the total value of trade registered consecutive negative growth.
By 2024, the import and export sector had begun to recover. In 2024 and 2025, the total value of trade grew by 7.3% and 15.5% year on year, respectively. Data for the first half of 2026 indicated that the total value of trade had already reached HK$7.1 trillion, a substantial year-on-year increase of 39.9%, with likelihood to reach a record high for the full year. Of this total, domestic exports amounted to approximately HK$37.1 billion, representing a significant increase of 36.9%.
Re-exports of AI-related goods drive trade prosperity
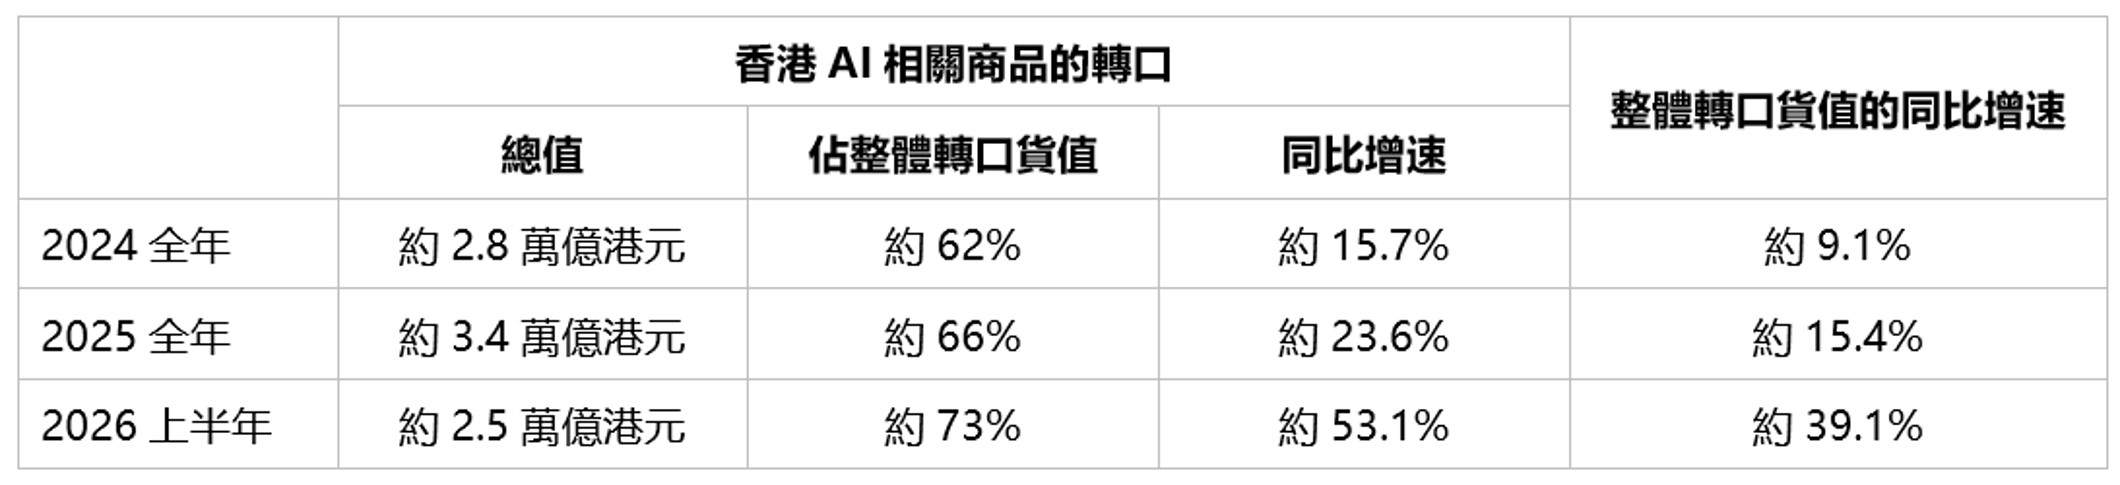
In this new round of growth, AI-related goods have played a leading role. As global demand for compute capacity has risen exponentially in recent years, AI hardware has entered a super cycle, with both volume and prices increasing. This has directly boosted the value of Hong Kong’s re-export trade (see Table).
Table Hong Kong’s re-exports of AI-related goods drive the trade recovery
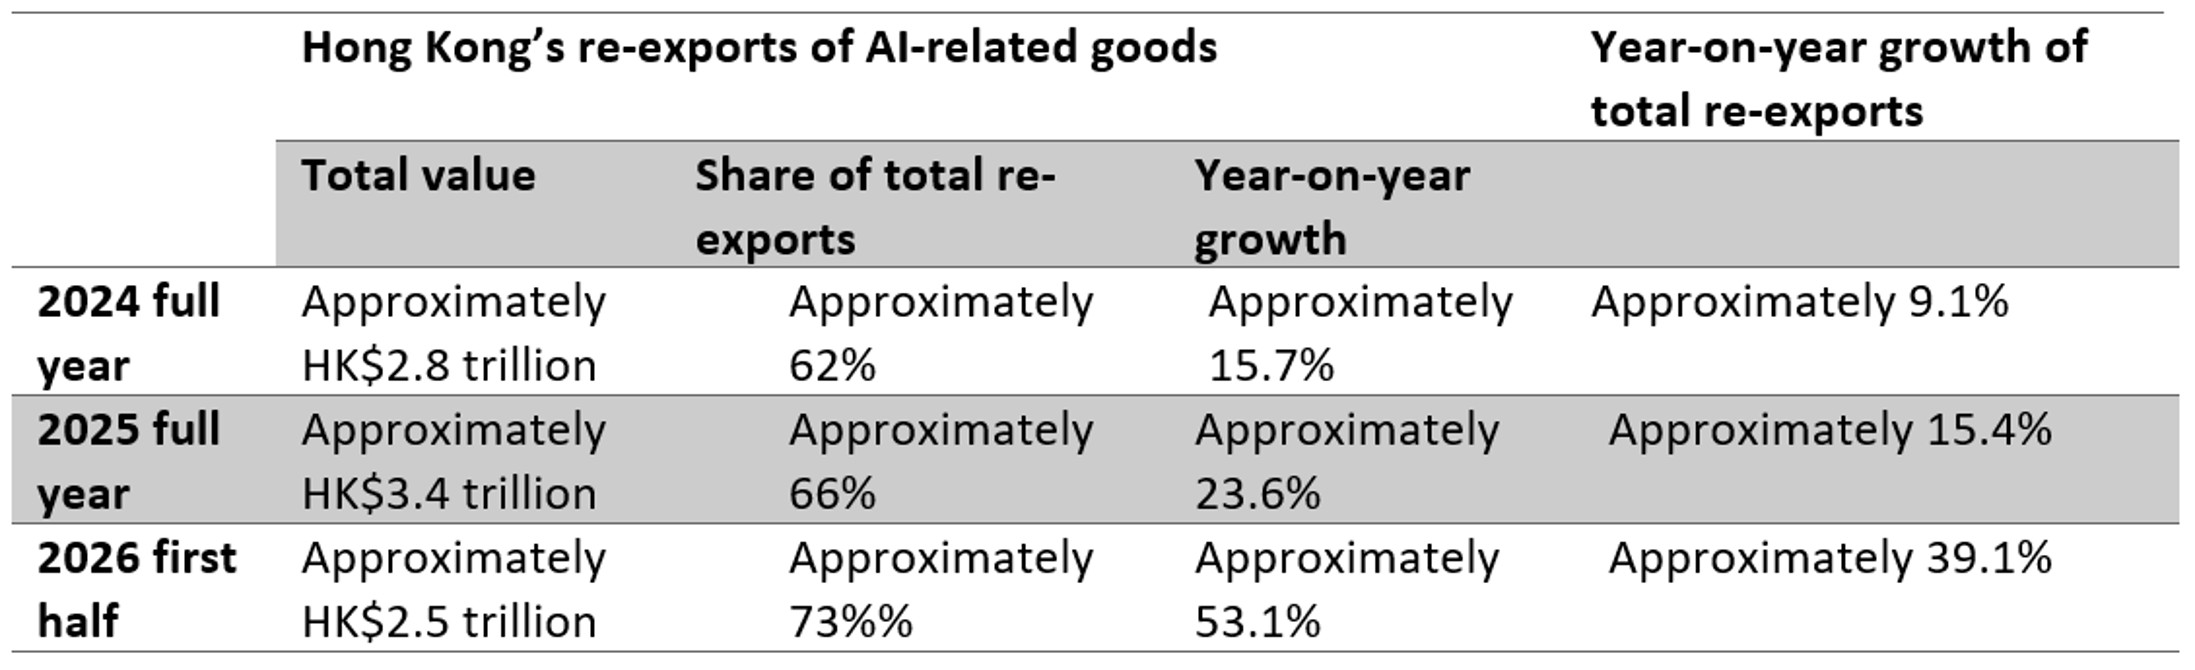
Source: Authors’ calculations based on data from Census and Statistics Department
These AI-related goods cover a broad range of products, including integrated circuits, processors, controllers, amplifiers, memory, automatic data processing machines, magnetic or optical readers, transistors, and solid-state non-volatile storage devices. Taken together, the above import and export data indicate that Hong Kong’s role as an international trade centre is being upgraded, with marked enhancement in both the technological content and the value of re-exported goods.
Mainland demand for compute capacity as the root, trade diversification as the branches
By origin of re-exports, the first half of 2026 showed a high degree of concentration. The four major origins together accounted for approximately 82% of the total, namely Mainland China (35.4%), China’s Taiwan region (20.6%), South Korea (13.1%), and Vietnam (12.6%). Although Mainland China and China’s Taiwan region remained the main origins, South Korea and Vietnam recorded particularly strong growth in re-export value, with year-on-year increases of 67% and 202%, respectively. In addition, although the next six origins together accounted for only 14% of the total, most of them also posted rapid year-on-year growth in re-export value.
This phenomenon is consistent with the current division of labour in the Asia-Pacific AI industry. Mainland China is home to leading technology companies such as Huawei, ChangXin Memory Technologies, and SMIC (Semiconductor Manufacturing International Corporation), and has large-scale production capacity across multiple categories of AI hardware. China’s Taiwan region, with the semiconductor giant TSMC (Taiwan Semiconductor Manufacturing Company Limited), dominates the global chip foundry sector. South Korea, supported by top-tier enterprises such as Samsung Electronics and SK Hynix, holds a dominant global position in areas such as high-bandwidth memory. Under the “China + 1” strategy, Vietnam has become a major destination for supply-chain relocation; in recent years, it has established numerous AI hardware packaging testing, and assembly production lines, thereby substantially expanding its production capacity. Other economies are also actively building AI infrastructure in an effort to secure a share of the opportunities created by the AI wave.
By re-export destination, in the first half of 2026, Mainland China accounted for an overwhelming share of 70%, with the re-export value rising sharply by 48.5% year on year. The second- to fourth-largest destinations together accounted for 17% of the total, with re-export values increasing at a robust pace. Ranked by growth rate, these three destinations were the US (109%), China’s Taiwan region (81%), and Vietnam (53%). Although the fifth- to seventh-largest destinations each accounted for less than 2% of the total, their growth rates were also noteworthy. This trade structure indicates that Hong Kong mainly serves the Mainland’s vast demand for compute capacity, while its customer base is gradually becoming more diversified.
An AI trade hub “backed by the motherland and connected to the world”
The trade data above demonstrate Hong Kong’s positioning as a city “backed by the motherland and connected to the world”. First, Hong Kong serves as a gateway for “bringing in” international resources. On the one hand, the Mainland imports AI hardware products from around the world through Hong Kong to meet its massive demand for compute capacity. On the other hand, AI hardware manufacturers worldwide gain access to the vast Mainland market through Hong Kong. As the Mainland’s indigenous AI hardware production capacity continues to expand, Hong Kong’s role is expected to expand accordingly, further assisting Mainland suppliers in “going global” and developing international markets.
Second, Hong Kong remains an important supply-chain hub. The AI hardware supply chain is highly complex and typically involves cross-border processes. For example, a chip may undergo various stages such as design in the Mainland, foundry production in China’s Taiwan region, and South Korea, and packaging testing in Vietnam. Together with tax and other considerations, the production process for AI products often generates enormous trade demand. Hong Kong is able to meet this demand not only because of its world-class logistics capabilities, but also because of its long-standing unique advantages as an international trade centre, including “One Country, Two Systems”, its status as a zero-tariff free port, the free flow of foreign exchange, and a common law system aligned with international practice. This is also the foundation for Hong Kong’s unique strategic role as a hub in the dual-circulation development of the national AI industry.
Capitalizing on the AI trade dividend to benefit the public
Amid the global AI revolution, Hong Kong has achieved remarkable growth in re-export value, while its trade structure is shifting towards high-tech and high value-added activities. It is clear that the economic dividend of the AI revolution is not confined to high-tech industries that are out of reach for the general public, but is also spilling over into traditional sectors such as trade and logistics. These sectors support the livelihoods of many people and small and medium-sized enterprises, and are of great significance to the city’s real economy.
Indeed, while celebrating this prosperity, we should not overlook the potential risks. The intensifying geopolitical rivalry between China and the US, supply-chain restructuring, regulatory changes around the world, and competition from neighbouring regions all create uncertainty for Hong Kong’s trade development and local employment prospects. In the face of these challenges, we need to continue consolidating Hong Kong’s position as a regional AI trade hub, with policy coordination and guidance being particularly vital. First, it is essential to maintain Hong Kong’s free-port system as well as improve compliance, risk-prevention, and risk-control mechanisms, so that Hong Kong’s trade can continue to earn the trust of the international community. Equally crucial is supporting the industry in upgrading towards smart operations, thereby improving the efficiency of trade and logistics services. In addition, support for local workers should also be optimized so that their skills meet market needs and they can share in the development dividend of trade in AI products. Finally, Hong Kong should continue to deepen cooperation with other cities in the Guangdong-Hong Kong-Macao Greater Bay Area, leveraging the overall strengths of the Area to enhance the competitiveness of its trade services.
Looking ahead, Hong Kong should proactively seize four major development opportunities. First, it should upgrade temperature-controlled warehousing and in-transit inspection services dedicated to high-end chips and hardware. Second, it should launch supply-chain finance tools, such as inventory financing and leasing, for high-unit-value AI hardware. Third, it should seize the development opportunities arising from AI software and applications, promote the development of trade in services such as intellectual property, and broaden Hong Kong’s role from an “AI hardware re-export port” to an “AI trade-in-services hub”. Fourth, Hong Kong should make good use of its strengths in fundamental AI research and actively participate in global AI governance, including standard-setting.